Independent Judgment for Complex Valuation
About | Valuation Economist
Valuation Economics — PPA, Transfer Pricing, IP & Intangibles, Enterprise & Infrastructure
Alpha Consulting Group provides independent valuation and economic analysis for enterprises, acquisitions, intellectual property and intangible assets, cross-border transactions, and infrastructure investments.
Our work combines financial valuation, transaction analysis, asset analysis, and practical economic judgment. We focus on conclusions that are understandable, supportable, and appropriate for financial reporting, tax planning, transactions, ownership transitions, restructuring, and management decision-making.
Enterprise Valuation
Enterprise valuation provides the broader economic framework for understanding an operating company, ownership interest, transaction, or strategic investment.
Our assignments may involve:
- Holding companies and multi-entity organizations
- Shareholder buyouts and consensual ownership transitions
- M&A and transaction valuation
- Operating companies and ownership interests
- Special-purpose entities
- Strategic and financial value
- Capital-intensive enterprises
- Transaction economics and financial modeling
The analysis may consider historical and expected financial performance, capital structure, ownership rights, market position, industry conditions, financing assumptions, transaction terms, and the realistic buyer or investor universe.
For M&A assignments, we distinguish between the financial value of an enterprise and the strategic value that a particular buyer may attribute to synergies, control, competitive positioning, or other transaction-specific benefits.
Purchase Price Allocation
We perform purchase price allocations for acquisitions involving privately held companies, operating enterprises, and complex asset groups.
Our analyses may include:
- Real property
- Machinery and equipment
- Other business personal property
- Customer-related intangible assets
- Trade names and trademarks
- Technology and intellectual property
- Contractual and other identifiable intangible assets
- Contributory asset requirements
- Deferred taxes and other adjustments
- Goodwill and going-concern value
An assembled workforce may also be considered when evaluating contributory asset requirements, although it ordinarily is not recognized as a separate acquired intangible asset under financial-reporting standards.
We evaluate how the acquired assets work together to generate earnings—not simply how they are classified for accounting purposes.
Connecting M&A Valuation and PPA
M&A valuation and purchase price allocation address different stages of the same transaction.
M&A valuation examines the enterprise, transaction economics, financial value, strategic value, and the reasonableness of negotiated consideration. Purchase price allocation begins after the consideration has been established and assigns acquisition-date value among the acquired assets and assumed liabilities under the applicable valuation framework.
The objective is not to force the transaction valuation and PPA to produce the same measure of value. It is to reconcile the underlying economic evidence and explain material differences among enterprise value, identifiable net assets, buyer-specific benefits, and residual goodwill.
IP & Intangible Asset Valuation
Intellectual property and intangible assets frequently connect enterprise valuation, M&A, PPA, transfer pricing, restructuring, and strategic transactions.
Our work may involve:
- Technology and patents
- Software and digital assets
- Trade secrets and proprietary know-how
- Trademarks, trade names, and brands
- Customer relationships
- Customer and supplier contracts
- Licensing and royalty arrangements
- Franchise and other contractual rights
- IP transfers and contributions
- Joint ventures and special-purpose entities
- Cross-border IP transactions
- Intangible assets in M&A and PPA
Our analysis begins with the economics of the intangible asset: the functions that create, support, maintain, protect, and exploit it; the associated assets; the risks assumed; its remaining economic life; and the economic benefits and returns it is expected to generate.
An intangible asset should not be valued as though it were economically detached from the business that creates, supports, protects, and exploits it.
This becomes particularly important for technology, software, brands, customer relationships, and contractual rights whose value may depend upon continuing investment, complementary assets, workforce activities, market position, infrastructure, or other enterprise capabilities.
One Asset — Different Valuation Questions
The same intangible may appear in several different valuation settings.
An acquisition may require M&A valuation and subsequently a purchase price allocation. A technology license may require royalty analysis. A related-party transfer may require transfer-pricing analysis. A restructuring or joint venture may require valuation of the economic rights being transferred or contributed.
The analytical tools may overlap, but the valuation purpose, unit of account, rights, assumptions, and economic perspective may differ.
The asset may be the same. The valuation question changes.
Transfer Pricing
We provide transfer-pricing documentation and economic analysis for U.S. and international companies engaged in cross-border related-party transactions.
Assignments may involve:
- Controlled product sales and distribution
- Management and support services
- Engineering and technical services
- Contract manufacturing
- Intercompany financing and guarantees
- Intellectual property and royalties
- IP transfers and cost-sharing arrangements
- Foreign-owned U.S. operating companies
- U.S. outbound transactions
- Asian inbound investment
- Annual testing and documentation updates
Our approach begins with the economics of the controlled transaction: the functions performed, assets employed, risks assumed, contractual relationships, market conditions, and level of income that comparable independent parties might reasonably expect.
Depending upon the facts, the analysis may apply operating-margin methods, comparable-company returns, royalty evidence, transactional evidence, or other recognized approaches.
IP, PPA & Transfer-Pricing Consistency
Intangible assets create an important connection between M&A, PPA, and transfer pricing.
An intangible identified during an acquisition may subsequently be licensed, transferred, developed, maintained, or exploited among related entities.
Values developed for PPA, IP valuation, licensing, and transfer pricing do not necessarily need to be identical because the purposes, standards, dates, rights, and assumptions may differ.
However, the underlying economic evidence should be reasonably consistent.
Consistency does not require identical values. It requires reconciliation of the underlying economics.
Enterprise & Infrastructure Valuation
Alpha Consulting Group has particular experience with capital-intensive enterprises and specialized infrastructure, including:
- Data centers and powered development sites
- Digital and telecommunications infrastructure
- Power generation and energy assets
- Nuclear and advanced-energy projects
- Industrial and manufacturing facilities
- Logistics and real-estate-intensive operating assets
- Data-center and energy special-purpose entities
For these assignments, valuation may need to reflect power availability, interconnection capacity, contractual rights, development timing, utilization, capital requirements, regulation, technological change, and long-term obsolescence.
Physical assets do not operate independently from contractual rights, operating capabilities, financing, customers, technology, and other intangible economic factors.
The analysis may therefore extend beyond conventional appraisal measures to consider operating capacity, capital recovery, execution risk, financing, contractual economics, and the realistic buyer or investor universe.
Valuation Economics as the Common Framework
Enterprise valuation, PPA, IP and intangible asset valuation, transfer pricing, and infrastructure valuation are not isolated disciplines.
They frequently involve the same underlying economic questions:
- What functions are being performed?
- What assets support those functions?
- What risks are being assumed?
- What contractual and economic rights exist?
- What continuing investment is required?
- What economic benefits and returns are expected?
- How long can those benefits reasonably continue?
- Which market participants or entities can realize them?
A useful analytical progression is:
Functions → Assets → Risks → Economic Benefits & Returns → Value
The specific valuation methodology follows from the economics of the assignment.
Methodology does not determine value. Economics determines which methodology is meaningful.
Independent, Multidisciplinary Perspective
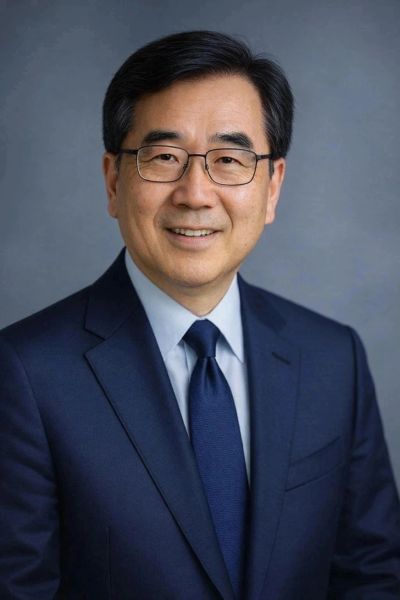
Alpha’s work is led by David Hahn, a valuation economist with experience spanning enterprise valuation, M&A analysis, intellectual property and intangible assets, real estate, machinery and equipment, financial analysis, transfer pricing, and infrastructure economics.
This multidisciplinary perspective is particularly useful when an assignment crosses traditional professional boundaries—for example, when an acquisition involves operating-company value, real estate, specialized equipment, technology, customer relationships, contractual rights, cross-border integration, and enterprise-level economics.
Professional Credentials
Professional designations and qualifications include:
- Certified Valuation Analyst (CVA)
- Accredited Senior Appraiser (ASA)
- Certified Merger & Acquisition Advisor (CM&AA)
- Master Analyst in Financial Forensics (MAFF)
- Certified Commercial Investment Member (CCIM)
- Certified General Real Estate Appraiser
- Master of Business Administration (MBA)
These qualifications support independent analysis for management, financial reporting, tax, transaction, audit-support, restructuring, and strategic decision-making purposes.
Technical and Academic Foundation
David Hahn earned a Bachelor of Science from San Jose State University, with studies in engineering technology and computer science, followed by graduate and executive education in business, finance, capital economics, and public-sector decision analysis.
His earlier professional software-engineering and technical systems experience contributes to a practical understanding of technology, software, facilities, equipment, contractual rights, and operating systems.
Combined with subsequent valuation experience involving intellectual property, intangible assets, enterprises, and infrastructure, this technical foundation is particularly relevant when economic value depends upon understanding how technology and physical assets actually function within an operating business.
Serving Clients Nationwide
Alpha Consulting Group serves privately held companies, investors, family ownership groups, M&A advisers, investment bankers, attorneys, accountants, financial executives, tax advisers, and international businesses throughout the United States.
Clients engage Alpha when an assignment requires independent judgment, multidisciplinary analysis, and a clear explanation of the economic substance behind the numbers.
Alpha Consulting Group
Enterprise & Infrastructure Valuation | Purchase Price Allocation | IP & Intangibles | Transfer Pricing